Safety first: This is general money education, not personalised financial advice. Please read our financial disclaimer before you start.
Key takeaways
- List bills by due date, then assign each one to the paycheck that arrives before it.
- Budget each paycheck to $0 as its own mini budget.
- Save half of rent from the second paycheck so the first one isn't swallowed.
- In 2027, Friday biweekly paydays starting January 1 give 27 paychecks; starting January 8 gives 26.
- Give each third paycheck a job ahead of time: savings, sinking funds or debt.
In this post12 sections
- What You'll Need
- Step 1: List Every Bill by Due Date
- Step 2: Assign Each Bill to Paycheck A or Paycheck B
- Step 3: Budget Each Paycheck to Zero
- Step 4: Smooth the Lumpy Bills
- Step 5: Plan the Third Paycheck Months (2027 Dates)
- Biweekly Budget Template (Free Printable)
- Example: Where Each $1,900 Paycheck Goes
- Biweekly Budget vs Monthly Budget: Which Fits You?
- Biweekly Budget Mistakes to Skip
- Variations: Couples, Uneven Pay and Weekly Pay
- FAQ
What You'll Need
Gather these first (about 30 minutes)
Step 1: List Every Bill by Due Date
Write each bill in date order, from the 1st to the 31st, with the amount next to it. Include anything that's automatic, like insurance or subscriptions. Seeing the dates in a line shows you where the crunch weeks are, which is the whole point of a biweekly budget.
| Bill | Amount | Due |
|---|---|---|
| Rent | $1,150 | 1st |
| Car payment | $320 | 10th |
| Internet | $55 | 12th |
| Utilities | $170 | 18th |
| Phone | $60 | 22nd |
| Car insurance | $120 | 25th |
| Credit card minimum | $90 | 28th |
Step 2: Assign Each Bill to Paycheck A or Paycheck B
Call the first paycheck of the month Paycheck A and the second Paycheck B. A simple rule: bills due from the 1st to the 14th come out of the paycheck that arrives before them, and bills due from the 15th to the 31st come out of the other one. If a bill lands right on payday, assign it to the earlier check so it's never late.
Your pay dates move a little each month because biweekly means every 14 days, not twice a month. That's why many people plan around the first and second paycheck of each month rather than fixed dates.
Step 3: Budget Each Paycheck to Zero
Now treat each paycheck as its own mini budget. Start with the bills you assigned, then split monthly costs like groceries, gas, savings and spending in half so each check carries its share. Keep going until every dollar of that paycheck has a job. That's the zero based budget idea applied to one paycheck at a time.
| Paycheck A ($1,900) | Amount | Paycheck B ($1,900) | Amount |
|---|---|---|---|
| Rent (half, plus half saved from last B) | $575 | Rent set-aside for next month | $575 |
| Car payment | $320 | Utilities | $170 |
| Internet | $55 | Phone | $60 |
| Groceries (half) | $300 | Car insurance | $120 |
| Gas (half) | $100 | Credit card minimum | $90 |
| Sinking funds | $75 | Groceries (half) | $300 |
| Savings | $100 | Gas (half) | $100 |
| Personal and household | $150 | Sinking funds | $75 |
| Extra credit card payment | $125 | Savings | $100 |
| Buffer | $100 | Personal and household | $150 |
| Buffer | $160 | ||
| Left to assign | $0 | Left to assign | $0 |
Step 4: Smooth the Lumpy Bills
Rent is the classic problem: one huge bill on the 1st and only one paycheck before it. The fix is to save half of it from Paycheck B for next month's rent, as the example does. After one month of setting it aside, rent stops eating a whole check.
Do the same for yearly and twice-a-year bills, like car insurance or registration. A small amount from every check goes into sinking funds, so the big bill is already covered when it arrives.
Step 5: Plan the Third Paycheck Months (2027 Dates)
Paid every two weeks means 26 paydays in most years, so two months get a third check. In 2027, if your first payday falls on Friday, January 1, you'll get 27 paydays that year. Plan with your own payroll calendar; these dates assume a Friday payday and no holiday shifts.
| Your first 2027 payday | Paydays in 2027 | Months with 3 paychecks |
|---|---|---|
| Friday, January 1 | 27 | January (1, 15, 29), July (2, 16, 30), December (3, 17, 31) |
| Friday, January 8 | 26 | April (2, 16, 30), October (1, 15, 29) |
Because your monthly bills are already covered by the first two checks, the third one is mostly free to assign. Decide its job now so it doesn't disappear. One example split of a $1,900 third check: $900 to the emergency fund, $600 to sinking funds like Christmas, and $400 extra on debt. If you're still building a cushion, see how much an emergency fund should be.
Savers who like a fixed amount every payday can pair this with our bi-weekly savings challenge charts.
Biweekly Budget Template (Free Printable)
Our free monthly budget sheet (PDF, 3 pages) includes a biweekly paycheck page with Paycheck A and Paycheck B columns, so you can copy the example above in pencil. No sign-up needed. The budget template guide explains each page.
Prefer Google Sheets or Excel? Make two columns, one per paycheck, list each assigned bill and category, and add a cell for each column that subtracts every line from that paycheck. When both cells show 0, you're done.
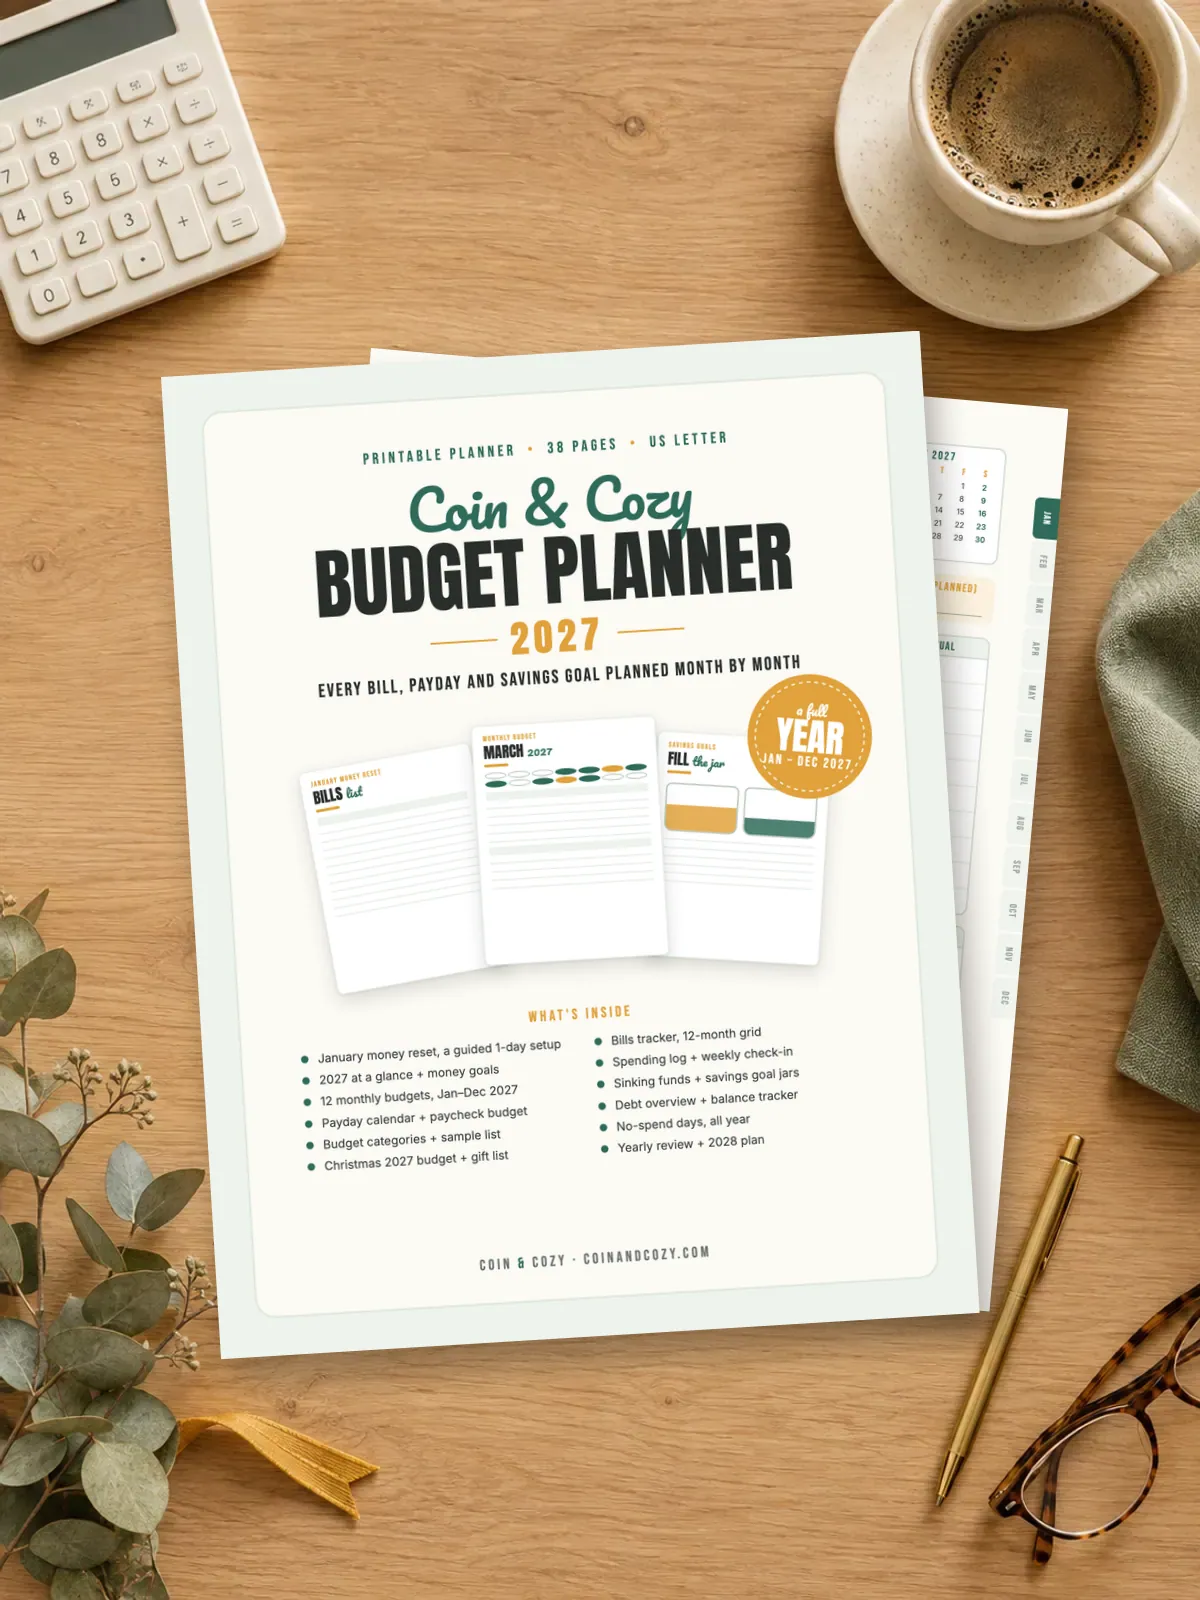
If you'd like the whole year planned out, the Cozy Budget Planner 2027 has a payday calendar and a paycheck budget page next to each monthly budget, plus sinking fund and debt trackers.
Example: Where Each $1,900 Paycheck Goes
Looking at the example as a whole: two $1,900 checks bring in $3,800 a month. Bills total $1,965, groceries and gas $800, savings and sinking funds $350, personal and household $300, extra debt $125 and buffers $260. Every dollar is assigned, and nothing waits on a paycheck that hasn't arrived yet.
If the buffer goes unused, roll it into next paycheck's savings. If a surprise uses it up, that's exactly what it was for.
Biweekly Budget vs Monthly Budget: Which Fits You?
A monthly budget works well when your income arrives once a month or when you already have a month of expenses sitting in checking. A biweekly budget fits better when money is tight between paychecks, when big bills cluster at the start of the month, or when you've ever paid a bill late while waiting for payday.
| Monthly budget | Biweekly budget | |
|---|---|---|
| Plans around | One month of income | Each paycheck as it arrives |
| Best for | Monthly pay or a cash cushion | Paid every two weeks, tight timing |
| Third paycheck | Often absorbed by spending | Planned ahead as a bonus |
| Rent on the 1st | Assumes the money is there | Builds the rent from both checks |
Plenty of people use both: a monthly plan for the big picture and a paycheck plan for timing. Our budget planner for beginners covers the monthly side step by step, and once you've been ahead for a few months, a monthly plan may feel easier.
Biweekly Budget Mistakes to Skip
Do this
- Budget each paycheck separately
- Save half of rent from the second check
- Give the third paycheck a job ahead of time
- Keep a small buffer in each check
Skip this
- Budgeting as if you get paid twice a month on fixed dates
- Counting the third paycheck as part of your regular monthly income
- Paying a bill late because it fell just before payday
- Letting each paycheck's leftovers drift into spending
Variations: Couples, Uneven Pay and Weekly Pay
Couples on different schedules: list both pay dates on one calendar and assign each bill to whichever check lands first before its due date. A short weekly money date keeps both people on the same page.
Uneven paychecks: plan each check around your lowest typical amount, then send anything extra to savings or debt once it arrives. Paid weekly? The same method works with four or five mini budgets a month; five-paycheck months are your bonus months.
A biweekly budget isn't about more money. It's about each paycheck knowing exactly what it's for.
If you're also paying down cards, our credit card debt payoff plan shows how to fit an extra payment into one of your two checks. For the planner, savings charts and Christmas planner together, the Cozy Money Binder bundles all three. This is general information, not financial advice.
Frequently asked questions
How do you budget biweekly paychecks?
List every bill by due date, assign each to the paycheck that arrives before it, then split groceries, gas, savings and spending between the two checks and budget each one to zero.
Which bills should come out of which paycheck?
A simple rule: the paycheck that arrives first in the month covers bills due from the 1st to the 14th, and the second covers the 15th to the 31st. Adjust so neither check is overloaded.
Which months have 3 paychecks in 2027?
For Friday biweekly paydays starting January 1, 2027: January, July and December. Starting January 8, 2027: April and October. Confirm with your payroll calendar, since holidays can shift dates.
What should I do with a third paycheck?
Since your bills are already covered, give it a planned job such as building your emergency fund, topping up sinking funds or paying extra on debt. These are examples, not financial advice.
How do I budget if rent is due on the 1st?
Set aside half of rent from your second paycheck each month. After one month, the first paycheck only needs to cover the other half.
Save it for later
Pin this to your Budgeting Basics board so it's there when you need it.
Save to Pinterest