Safety first: This is general money education, not personalised financial advice. Please read our financial disclaimer before you start.
Key takeaways
- 50% needs, 30% wants, 20% savings and extra debt payments, all from take-home pay.
- Minimum debt payments count as needs; anything above the minimum counts toward the 20%.
- On $4,000 take-home: $2,000 needs, $1,200 wants, $800 savings. Example numbers only.
- It breaks when housing is high: 49.7% of renter households were cost-burdened in 2023 (Census).
- If needs run over 50%, try 60/20/20 or a zero-based budget instead of forcing the split.
In this post7 sections
Quick note: product links go to Amazon search results or our own shop, and we may earn a small commission if you buy, at no extra cost to you. Dollar amounts below are examples to show the math. Personal organizing tool, not financial advice.
What Is the 50/30/20 Rule?
The 50/30/20 rule is a percentage budget. You do not track every category; you check that three big buckets stay near their share of the money that actually lands in your bank account.
It was popularized by Elizabeth Warren and her daughter Amelia Warren Tyagi in their book All Your Worth (Wikipedia, Amelia Warren Tyagi). The appeal is that it takes five minutes: three numbers, one check a month.
| Question | Short answer |
|---|---|
| What are the three parts? | 50% needs, 30% wants, 20% savings and extra debt payments |
| Gross or take-home pay? | Take-home pay, after taxes and paycheck deductions |
| Where do minimum debt payments go? | Needs |
| Where do extra debt payments go? | The 20% |
| Who is it best for? | Steady paychecks and housing that fits inside the needs half |
| Where does it break? | High rent, low income, big debt or irregular pay |
What Counts as Needs, Wants and Savings?
Needs are the bills you must pay to live and work: rent or mortgage, utilities, groceries, insurance, transportation to work, childcare and minimum debt payments.
Wants are everything you could cut in a hard month: eating out, streaming, shopping, hobbies, travel and upgrades like a bigger phone plan.
Savings and debt is the 20%: the emergency fund, retirement you add yourself, sinking funds and any payment above a debt minimum. A gray area like a gym membership goes wherever you would honestly cut it.
A Worked Example of the 50/30/20 Rule on $4,000 Take-Home
Here is the 50/30/20 rule on a $4,000 monthly take-home for a renter in a mid-cost area. This is an example to show the split, not a recommended budget.
| Bucket | Line | Per month (example) |
|---|---|---|
| Needs (50%) | Rent | $1,150 |
| Needs (50%) | Utilities and phone | $220 |
| Needs (50%) | Groceries | $380 |
| Needs (50%) | Gas and car insurance | $200 |
| Needs (50%) | Minimum debt payment | $50 |
| Needs total | $2,000 | |
| Wants (30%) | Eating out and takeout | $250 |
| Wants (30%) | Streaming and subscriptions | $60 |
| Wants (30%) | Clothes and shopping | $200 |
| Wants (30%) | Hobbies and fun | $240 |
| Wants (30%) | Gifts and holidays | $150 |
| Wants (30%) | Travel fund | $300 |
| Wants total | $1,200 | |
| Savings and debt (20%) | Emergency fund | $400 |
| Savings and debt (20%) | Retirement (IRA) | $250 |
| Savings and debt (20%) | Extra debt payment | $150 |
| Savings and debt total | $800 | |
| Take-home total | $4,000 |
Notice how tight the needs half is with $1,150 rent. Push rent to $1,600 and needs land at $2,450, or 61%, before anything else changes.
Where the 50/30/20 Rule Breaks
The rule assumes housing fits inside the needs half. For many families it does not. In the 2023 American Community Survey, 49.7% of renter households were cost-burdened, meaning they spent more than 30% of income on housing, and over 21 million of 42.5 million renter households were in that group (US Census Bureau, September 12, 2024).
Housing is also the largest line in average spending: $26,266 of $78,535 a year, 33.4%, for all US households in 2024 (BLS Consumer Expenditures 2024, December 19, 2025). Add groceries, insurance and a car and needs pass 50% fast.
| Myth | Reality |
|---|---|
| Everyone should hit 50/30/20. | It is a starting split. In high-rent cities needs often run 60% or more. |
| It uses gross income. | It uses take-home pay. Gross numbers make the needs half look roomier than it is. |
| Debt payments are wants. | Minimums are needs; extra payments count toward the 20%. |
| If you miss the split, you failed. | Missing it tells you which bucket to fix: usually housing or debt. |
Alternatives: Zero-Based, 60/20/20 and 70/20/10
| Method | Split | Use it when |
|---|---|---|
| 50/30/20 | 50 needs, 30 wants, 20 savings | Housing and bills fit in half of take-home |
| 60/20/20 | 60 needs, 20 wants, 20 savings | High rent or childcare, but you still want to save 20% |
| 70/20/10 | 70 spending, 20 savings, 10 debt or giving | Needs and wants are hard to separate |
| Zero-based | Every dollar assigned until zero is left | Tight months, irregular pay or paying off debt |
A zero-based budget is the most hands-on option and works on any income because it starts from your real bills, not a percentage. For a full first budget, the beginner budget planner guide walks through the setup, and how much a family of 4 budgets per month shows real spending by category from BLS.
Try the 50/30/20 Rule on Paper
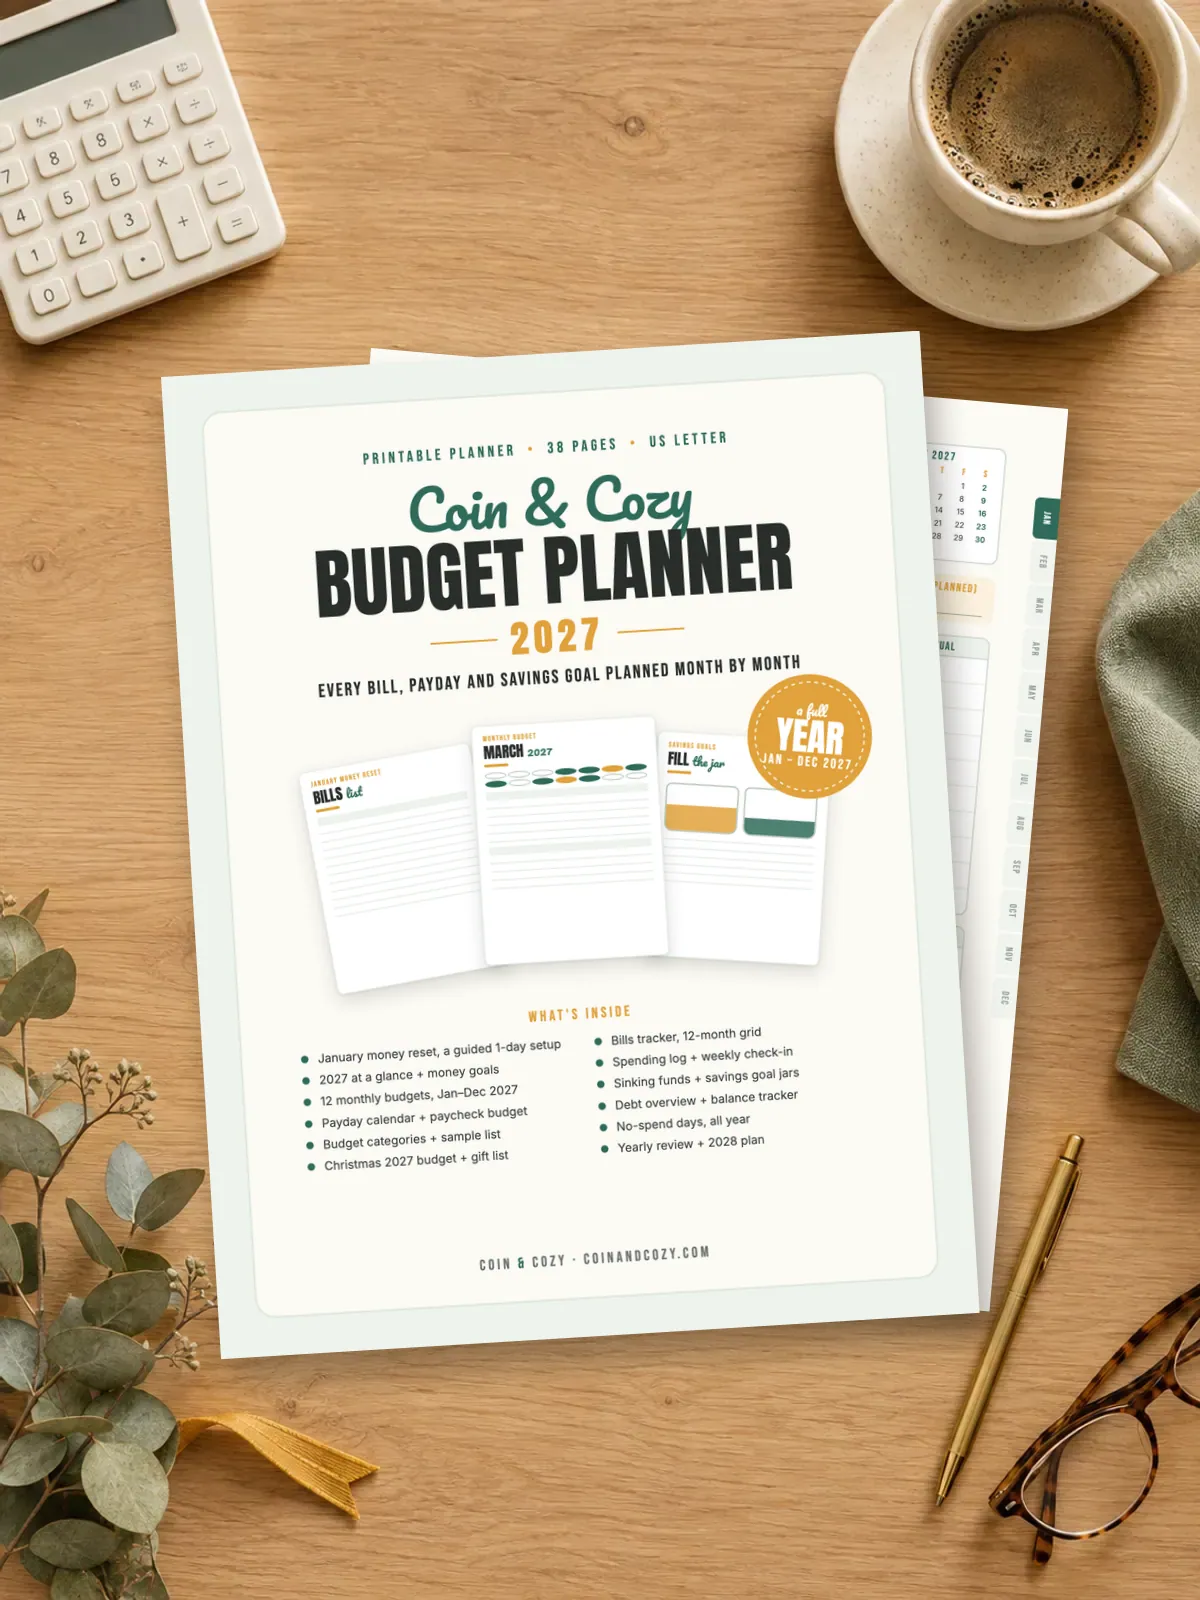
Write your take-home pay on a free monthly budget sheet, add up needs, wants and savings, and divide each by take-home pay. If needs are over 50%, pick the alternative that fits. The Cozy Budget Planner 2027 has a budget categories page with a note on the 50/30/20 idea, 12 monthly budgets and sinking fund trackers. Personal organizing tool, not financial advice.
Frequently asked questions
What is the 50/30/20 rule?
A budget that splits take-home pay into 50% needs, 30% wants and 20% savings and extra debt payments. On $4,000 a month that is $2,000, $1,200 and $800.
Is the 50/30/20 rule realistic?
For many people it is a stretch, mainly because of housing. Census data show 49.7% of renter households spent more than 30% of income on housing in 2023. Use it as a check, and switch to 60/20/20 or zero-based if needs run high.
Does the 50/30/20 rule use gross or net income?
Net, meaning take-home pay after taxes and paycheck deductions. If retirement is already taken from your paycheck, you can count it toward the 20%.
What is the 60/20/20 rule?
A variation that allows 60% for needs, 20% for wants and 20% for savings. It keeps the savings rate and takes the extra room for needs out of wants.
What is the 70/20/10 rule?
70% for spending (needs and wants together), 20% for savings and 10% for debt payoff or giving. It suits people who find needs and wants hard to separate.
Save it for later
Pin this to your Budgeting Basics board so it's there when you need it.
Save to Pinterest