Safety first: This is general money education, not personalised financial advice. Please read our financial disclaimer before you start.
Key takeaways
- 12 tasks at about 15 minutes each make 4 sessions of 45 minutes and about 3 hours in total (our arithmetic).
- Net worth is assets minus debts; the example snapshot is $13,000 minus $8,900, or $4,100 (made-up numbers).
- The FTC says the three nationwide credit bureaus offer free weekly reports at AnnualCreditReport.com.
- IRS Publication 969 says a health FSA can offer a grace period or a limited carryover, but not both, and some plans offer neither.
- If you only have 30 minutes, check your FSA, cancel unused subscriptions and pull your credit reports.
In this post21 sections
- Why an End of Year Financial Checklist Works Better in November
- Pick Your Four Session Dates
- Session 1: Take a Snapshot of Where You Stand
- Task 1: Net Worth Snapshot
- Task 2: Scan Your Statements for Errors
- Task 3: Pull Your Credit Reports
- Session 2: Cut What You Do Not Use
- Task 4: Subscription Audit
- Task 5: Annual Bills Calendar
- Task 6: Benefits and FSA Check
- Session 3: Strengthen Your Savings
- Task 7: Emergency Fund Check
- Task 8: Retirement and HSA Check
- Task 9: Start Next Year's Sinking Funds
- Session 4: Get Your Paper and Plans in Order
- Task 10: Tax Document Folder
- Task 11: Donation and Receipt Log
- Task 12: Write Your 2027 Goals
- If You Only Have 30 Minutes
- Keep the Results Where You Can Find Them
- FAQ
Quick note: product links go to Amazon search results or our own shop, and we may earn a small commission if you buy, at no extra cost to you. Dollar amounts are labelled examples, not advice about your money, and prices change by store and week. This is general information, not financial, tax or legal advice; ask a qualified professional about your own situation.
Why an End of Year Financial Checklist Works Better in November
A year-end money check is easy to skip in the middle of holiday shopping. The trouble is that some of it has a hard date. Many employer plans run on the calendar year, so the last payday that counts for 2026 is a December one, and some benefit balances do not carry over. Checking in November leaves time to act.
This checklist has 12 tasks of about 15 minutes each, grouped into 4 sessions of about 45 minutes (our arithmetic: 12 tasks at 15 minutes is 180 minutes, or 3 hours). It is a different job from building next year's budget, which our New Year budget plan covers. This one closes out 2026.
| Session | Task | Have open |
|---|---|---|
| 1: Snapshot | 1. Net worth snapshot | Bank, loan and card balances |
| 1: Snapshot | 2. Scan statements for errors | Last three statements |
| 1: Snapshot | 3. Pull your credit reports | AnnualCreditReport.com |
| 2: Cut | 4. Subscription audit | Card and bank statements |
| 2: Cut | 5. Annual bills calendar | Insurance and renewal emails |
| 2: Cut | 6. Benefits and FSA check | Benefits portal |
| 3: Save | 7. Emergency fund check | Savings balance and monthly bills |
| 3: Save | 8. Retirement and HSA check | Payroll stubs and account pages |
| 3: Save | 9. Start next year's sinking funds | Notebook or planner |
| 4: Paper | 10. Tax document folder | Folder or envelope |
| 4: Paper | 11. Donation and receipt log | Receipts and emails |
| 4: Paper | 12. Write 2027 goals | Planner |
Pick Your Four Session Dates
Thanksgiving is Thursday, November 26, and Christmas is Friday, December 25. Put the four sessions on the calendar now, before the month fills up.
| Session | Suggested date | Tasks |
|---|---|---|
| 1 | Sunday, November 8 | Net worth, statement scan, credit reports |
| 2 | Sunday, November 15 | Subscriptions, annual bills, benefits and FSA |
| 3 | Sunday, November 22 | Emergency fund, retirement and HSA, sinking funds |
| 4 | Sunday, December 6 | Tax folder, donation log, 2027 goals |
Session 1: Take a Snapshot of Where You Stand
Start by seeing the whole picture. You cannot decide what to change until you know where you are.
Task 1: Net Worth Snapshot
Net worth is what you own minus what you owe. Write each account balance on one page, add the assets, add the debts and subtract. The number can be small or even negative; the point is to repeat it next December and see the direction.
| Item | Amount |
|---|---|
| Checking | $1,800 |
| Savings | $2,200 |
| Retirement account | $9,000 |
| Total assets | $13,000 |
| Credit card | $2,400 |
| Car loan | $6,500 |
| Total debts | $8,900 |
| Net worth ($13,000 minus $8,900) | $4,100 |
Task 2: Scan Your Statements for Errors
Look at the last three months of bank and card statements. Mark any charge you do not recognize, any double charge and any fee. Call the bank about anything odd. This takes longer than it should for most people because we rarely read statements, which is why it deserves its own 15 minutes.
Task 3: Pull Your Credit Reports
The Federal Trade Commission says the three nationwide credit bureaus offer free weekly reports at AnnualCreditReport.com (FTC). Look for accounts you do not recognize, old addresses and late payments that are not yours. If something is wrong, dispute it with the bureau and the company; the FTC has a guide to disputing errors.
Session 2: Cut What You Do Not Use
Now find money you are already spending. It is the fastest way to start the year ahead.
Task 4: Subscription Audit
List every monthly charge: streaming, music, apps, memberships, meal kits and cloud storage. Mark each one use, maybe or never. Cancel the "never" items today and set a reminder to review the "maybe" items in March.
| Subscription | Monthly | Keep or cancel |
|---|---|---|
| Streaming A | $12 | Keep |
| Streaming B | $9 | Cancel |
| Music app | $11 | Keep |
| Cloud storage | $3 | Keep |
| Meal kit | $48 | Cancel |
| Phone app | $7 | Cancel |
| Gym | $15 | Keep |
| Total | $105 | |
| Cancelled ($9 + $48 + $7) | $64 a month, $768 a year |
In this example, three cancellations save $64 a month, which is $768 a year (our arithmetic). Your own numbers will differ.
Task 5: Annual Bills Calendar
Put every once-a-year bill on one calendar: car registration, insurance, domain names, memberships and anything that renews by email. Next to each, write the month you will start saving for it. Our sinking funds guide shows how to divide each bill into monthly amounts.
Task 6: Benefits and FSA Check
If your job offers a health flexible spending account (FSA), check the balance and the deadline. IRS Publication 969 says an FSA plan can offer a grace period of up to 2.5 months or a limited carryover, but not both, and some plans offer neither, so unspent money can be lost (IRS Publication 969). Look at your plan documents for the exact rule and use the balance on eligible items you already need.
Session 3: Strengthen Your Savings
Task 7: Emergency Fund Check
Divide your savings by one month of must-pay bills to see how many months you have covered. Example: $2,200 saved and $2,400 of monthly essentials is about 0.9 months (our arithmetic). If you have less than one month, start with the first small step in our low-income emergency fund guide; if you have more, see how much your fund should be.
Task 8: Retirement and HSA Check
Look at your payroll stubs and account pages. Are you getting any employer match your plan offers? Employer plans usually run on the calendar year, so December paychecks are the last that count for 2026. If you have a health savings account, ask your plan administrator about the contribution deadline. This is not advice on how much to save; it is a check that nothing you are entitled to goes unclaimed.
Task 9: Start Next Year's Sinking Funds
Next December's gifts and trips are cheaper to cover in twelve parts than in one. Divide a target by 12 and decide which account holds it. For Christmas, our Christmas sinking fund guide gives monthly amounts for several goals.
Session 4: Get Your Paper and Plans in Order
Task 10: Tax Document Folder
Make one folder, paper or digital, and put tax paperwork in it as it arrives. Employers generally must send W-2 forms by January 31, and other forms such as 1099s may arrive later, so the folder fills through the winter.
What to put in the folder
Task 11: Donation and Receipt Log
List every donation you made this year with the date, the charity and the amount. Save receipts and acknowledgment emails. If you plan to give before December 31, set the amount first so it fits your budget.
Task 12: Write Your 2027 Goals
Finish with the part that looks ahead. Pick three goals for 2027 and put a number and a date on each. Our financial goals for 2027 list has examples, and the New Year budget plan turns them into a monthly plan in one evening.
If You Only Have 30 Minutes
If the month gets away from you, do these three first. They are the ones with dates and the ones that save the most money.
-
Step 1: Check your FSA balance and deadline
Unspent FSA money can be lost, so this one has a real date. Log in or check your plan paperwork.
-
Step 2: Cancel the subscriptions you never use
List monthly charges and cancel any marked never. Every cancellation is a saving that repeats each month.
-
Step 3: Pull your credit reports
Scan for accounts or addresses you do not recognize. It takes ten minutes and protects you all year.
Then book the other three sessions in your calendar before you close the laptop.
Keep the Results Where You Can Find Them
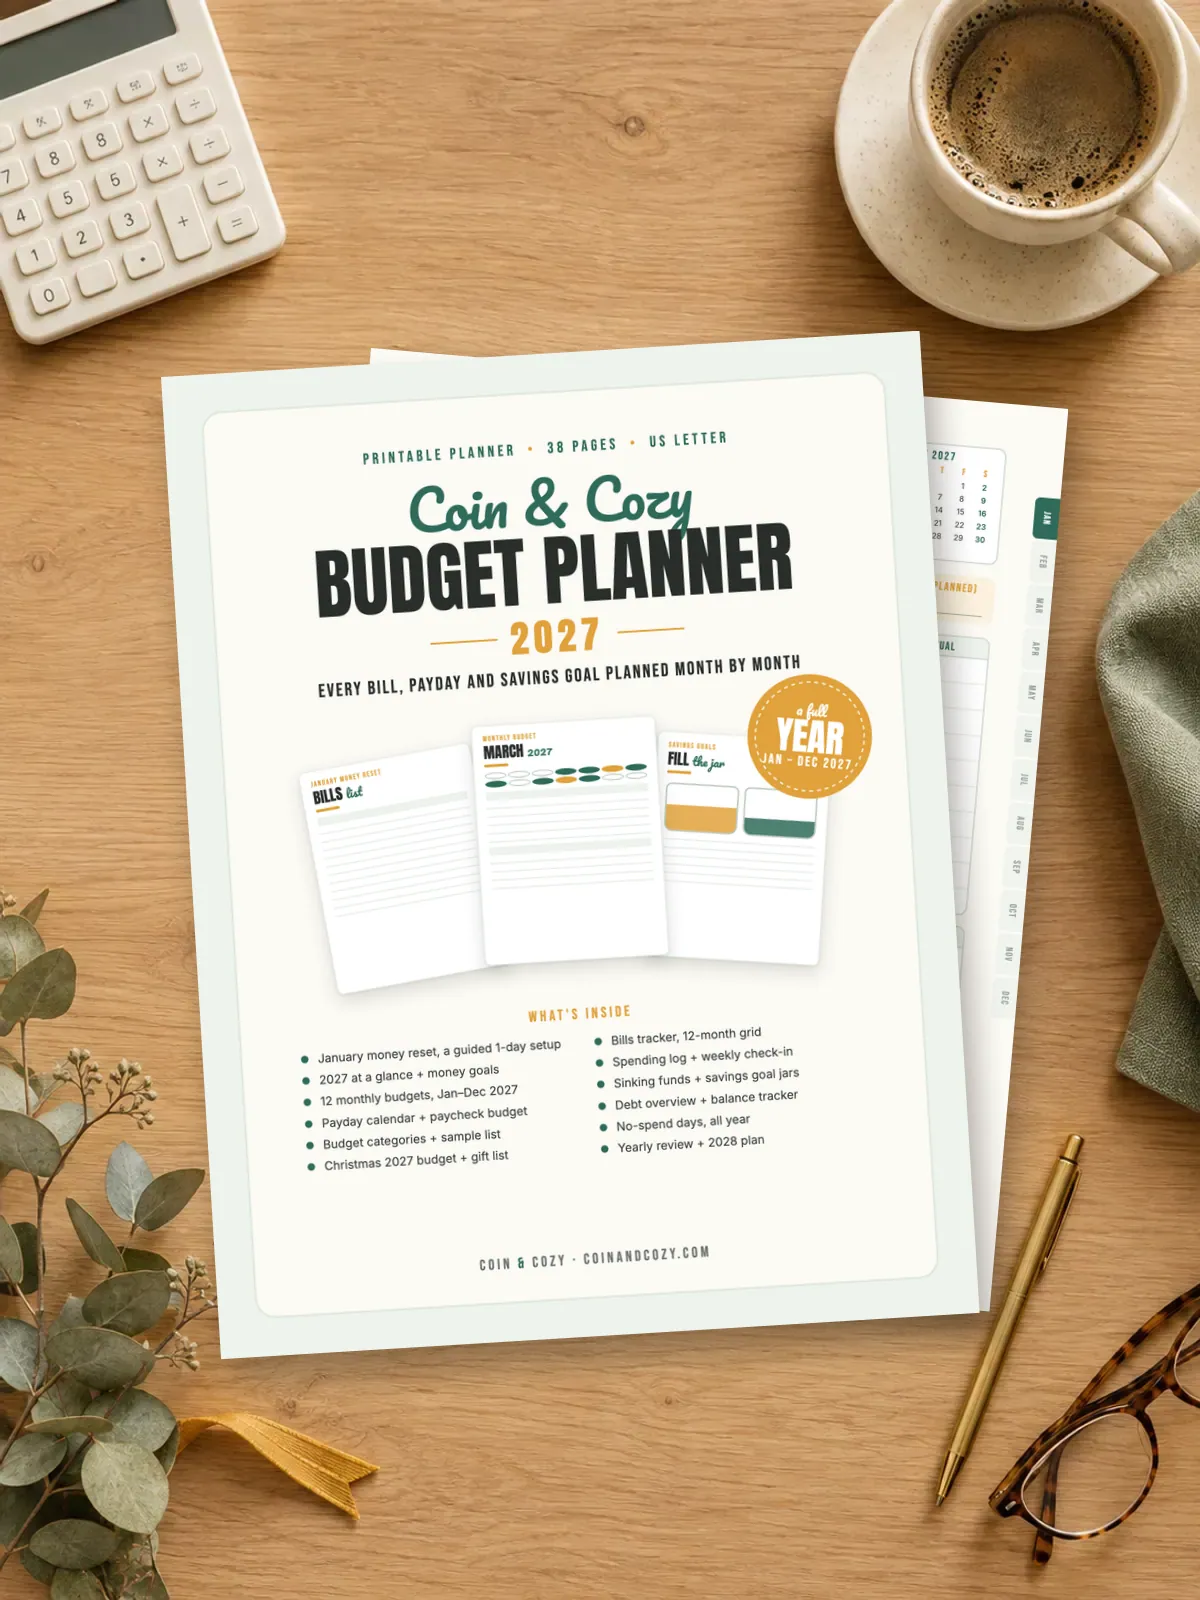
Write the date and your numbers on one page: net worth, subscriptions cancelled, emergency fund months, goals. A printable binder keeps it all together, and the shop's money binder has pages for each of these lines. If you would rather keep it digital, one note on your phone works too.
Frequently asked questions
What should be on an end of year financial checklist?
A net worth snapshot, a statement scan, credit reports, a subscription audit, an annual bills calendar, a benefits and FSA check, an emergency fund check, a retirement and HSA check, sinking funds, a tax folder, a donation log and goals for next year.
How long does an end of year financial review take?
About 3 hours in our plan: 12 tasks at 15 minutes each, split into four 45-minute sessions. It may take less if your records are in order.
What money tasks should I finish before December 31?
Check any health FSA balance and plan deadline, confirm your payroll retirement or HSA contributions, and make any charitable gifts you planned. Plan rules vary, so check your own documents.
How do I get my free credit reports?
The FTC says the three nationwide credit bureaus offer free weekly reports at AnnualCreditReport.com.
What is the difference between this and a New Year budget?
This closes out the current year with a check-up and a clean-up. A New Year budget builds the plan for the next one. Do this first, then the budget.
Is this tax advice?
No. It is a general checklist. Ask a qualified tax professional about deductions, deadlines and your own situation.
Save it for later
Pin this to your Budgeting Basics board so it's there when you need it.
Save to Pinterest