Safety first: This is general money education, not personalised financial advice. Please read our financial disclaimer before you start.
Key takeaways
- The classic 52 week savings challenge totals $1,378, about $26.50 a week on average.
- Counting up puts $598, about 43% of the total, in the last 13 weeks, which lands in October to December if you start in January.
- The reverse version saves the big weeks first, so December is the easy part.
- Half size totals $689 and quarter size totals $344.50, so tight budgets can still finish.
- Paid every two weeks? $53 a paycheck for 26 paychecks also reaches $1,378.
In this post11 sections
- How the 52 Week Savings Challenge Works (and Its December Problem)
- Way 1: The Classic Count-Up (Start It in the Fall)
- Way 2: The Reverse 52 Week Savings Challenge
- Way 3: Pick Any Box (For Uneven Paychecks)
- Way 4: Resize the Steps to Fit Your Budget
- Way 5: Save the Same Amount Every Week or Payday
- Which Way Fits Your Budget?
- Where to Keep the Money
- How to Stay on Track for 52 Weeks
- Common Mistakes With the 52 Week Money Challenge
- FAQ
| Way | How it works | Year total | Best for |
|---|---|---|---|
| 1. Classic count-up | $1 week 1, up to $52 week 52 | $1,378 | Steady income, starting in fall |
| 2. Reverse | $52 week 1, down to $1 week 52 | $1,378 | Anyone who dreads December |
| 3. Pick any box | Color any unused amount from $1 to $52 each week | $1,378 | Uneven paychecks, tips, gig work |
| 4. Resized steps | $0.25, $0.50, $2 or $5 steps instead of $1 | $344.50 to $6,890 | Tight budgets or bigger goals |
| 5. Flat amount | Same amount every week or payday | You choose | Paycheck planners who like simple |
How the 52 Week Savings Challenge Works (and Its December Problem)
The rule is simple. Each week you save the number of that week in dollars, so week 10 is $10 and week 52 is $52. Add up all 52 weeks and you get $1,378.
Here's the catch most charts skip. The early weeks are tiny, but weeks 40 to 52 add up to $598, about 43% of the whole year. Start in January and those big weeks fall from early October through the end of December, right when gifts, travel and heating bills show up.
That doesn't mean the challenge is broken. It means you should pick a version that puts the big weeks where your budget has room. The 5 ways below all reach a real number, and each one solves a different problem.
Way 1: The Classic Count-Up (Start It in the Fall)
This is the original. You save $1, then $2, then $3, and the chart fills in order. It feels easy for months, which is why so many people start it.
| Weeks | You save each week | Quarter total | Running total |
|---|---|---|---|
| 1 to 13 | $1 to $13 | $91 | $91 |
| 14 to 26 | $14 to $26 | $260 | $351 |
| 27 to 39 | $27 to $39 | $429 | $780 |
| 40 to 52 | $40 to $52 | $598 | $1,378 |
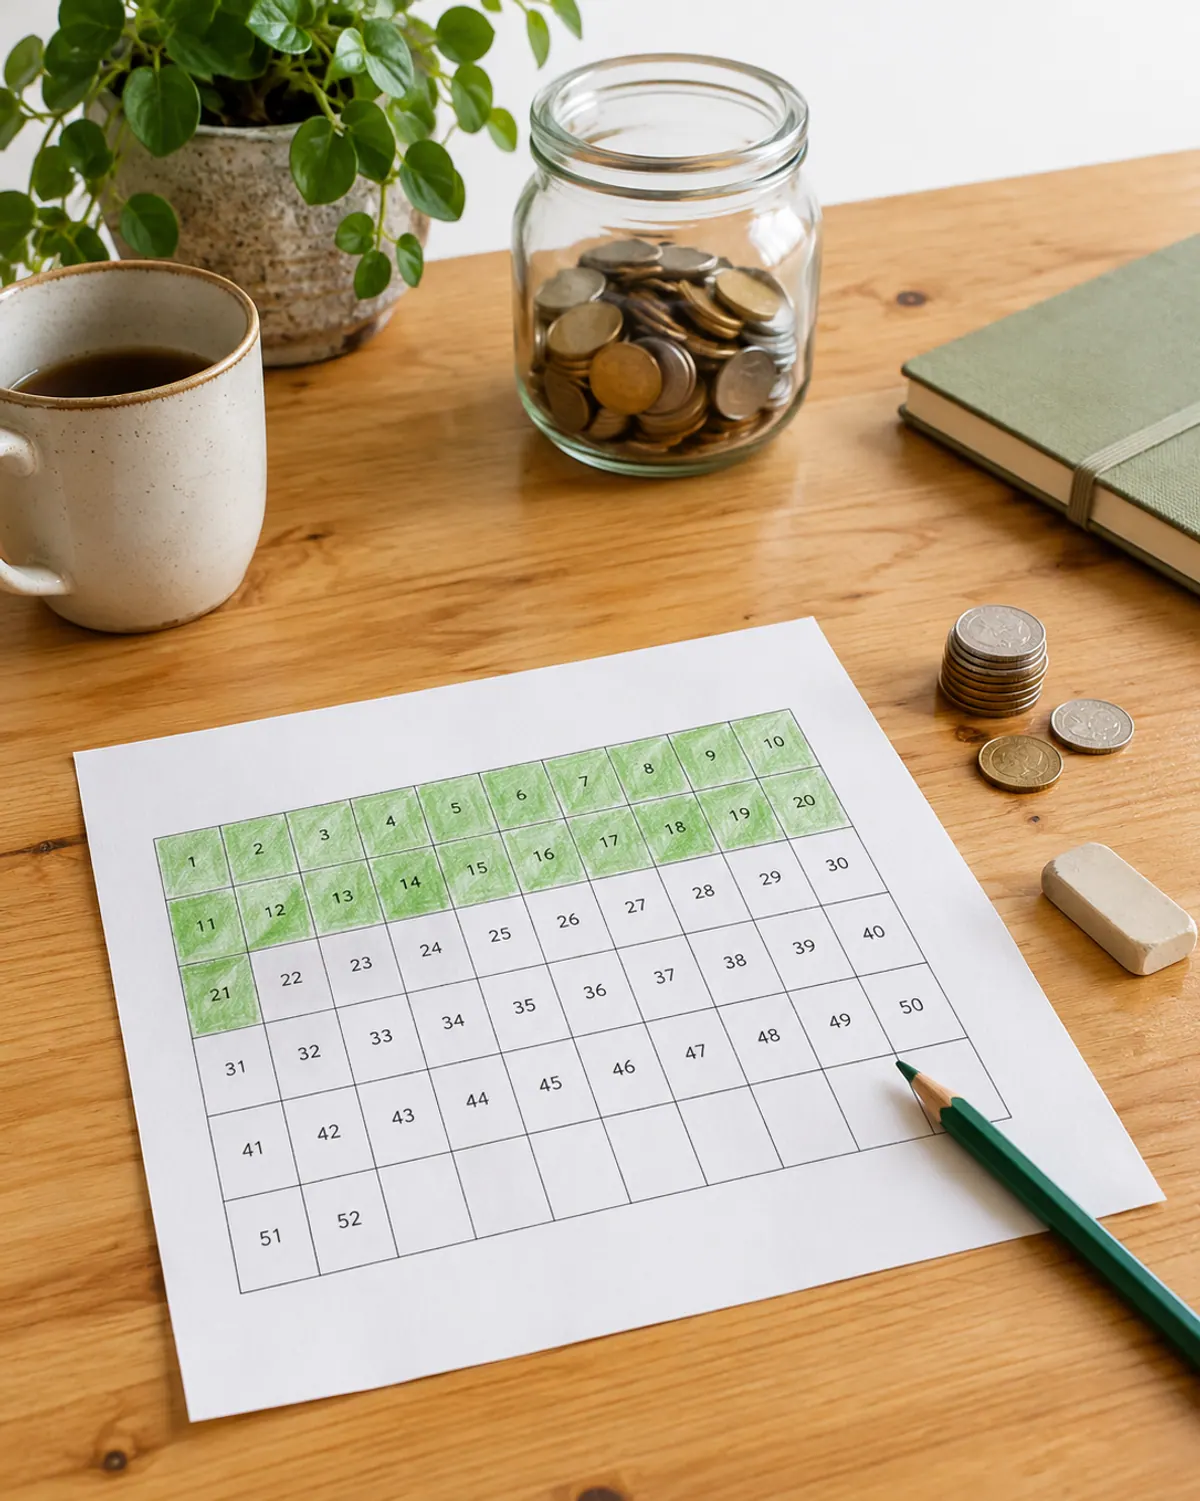
The fix for December is your start date. If you start the week of October 19, 2026, week 40 begins around July 19, 2027 and week 52 around October 11, 2027. The heavy weeks land in summer and early fall, and you reach $1,378 before the holidays.
Way 2: The Reverse 52 Week Savings Challenge
Flip the chart. Week 1 is $52, week 2 is $51, and you count down to $1 in the final week. The total is the same $1,378.
Starting in January, the first 13 weeks take $598 and the last 13 take only $91. That means the hardest weeks come right after the holidays, when many people are in a "fresh start" mood, and December asks for $1 to $4 a week.
The reverse way is hard for one group: anyone already behind on bills in January. If that's you, try the resized or flat versions first and come back to reverse next year.
Way 3: Pick Any Box (For Uneven Paychecks)
Print a chart with the numbers 1 to 52 and color any one box each week. A good week, you cross off $45. A thin week, you cross off $3. When every box is gone, you have $1,378.
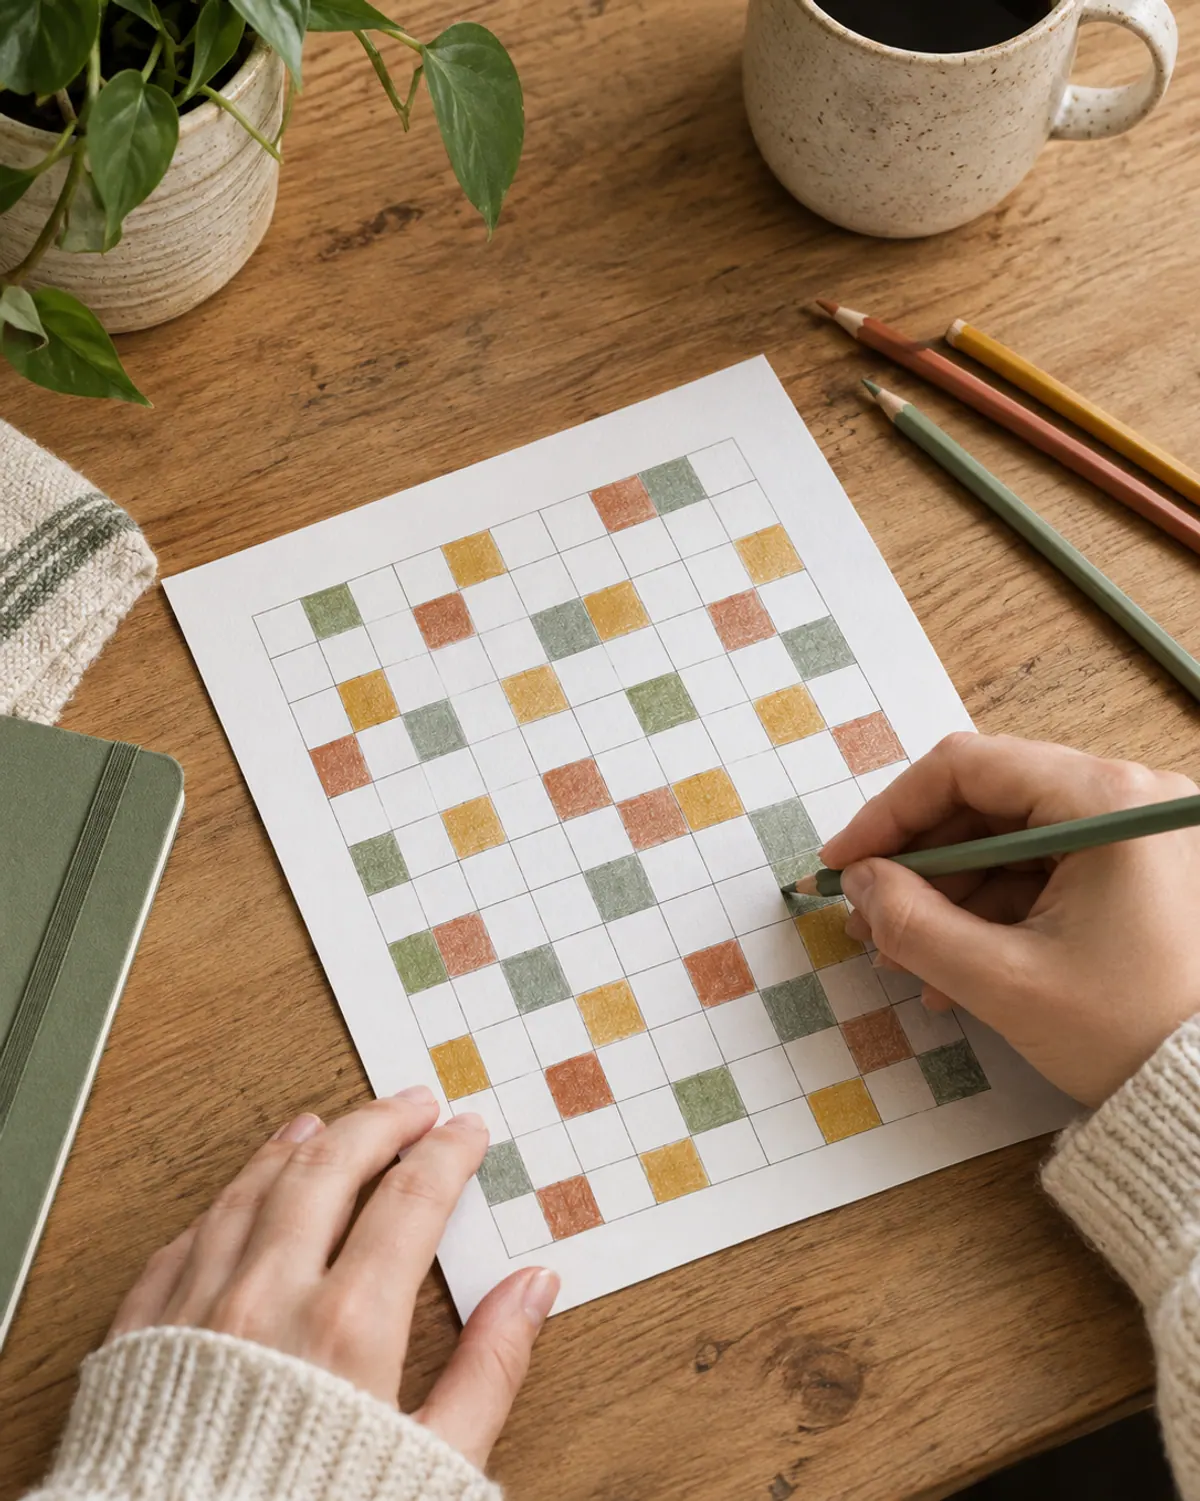
This version suits tips, gig work, commission or hours that change. It also works for couples, since either person can color a box when they have extra.
One rule keeps it honest: save the big numbers when money is good. If you only pick small boxes for months, you end up with a row of $40s and $50s at the end, which is the same December problem in a new shape.
Way 4: Resize the Steps to Fit Your Budget
The $1 step is just a starting point. Change the step size and the whole challenge shrinks or grows with it. Every version below still runs 52 weeks.
| Step size | Week 1 | Week 52 | Average per week | Year total |
|---|---|---|---|---|
| Quarter ($0.25) | $0.25 | $13 | $6.63 | $344.50 |
| Half ($0.50) | $0.50 | $26 | $13.25 | $689 |
| Classic ($1) | $1 | $52 | $26.50 | $1,378 |
| Double ($2) | $2 | $104 | $53 | $2,756 |
| Five ($5) | $5 | $260 | $132.50 | $6,890 |
The quarter and half versions are a real option when money is tight. $344.50 is still a starter emergency cushion that many people would not have otherwise. See how much an emergency fund should be for where that first goal could go.
Bigger steps need a reality check. Week 52 of the $5 version is $260, so only pick it if that fits a normal week of your budget.
Way 5: Save the Same Amount Every Week or Payday
If you get paid every two weeks, a weekly chart can feel like extra work. Save $53 a paycheck for 26 paychecks and you land on the same $1,378, with no December spike. Weekly, that's $26.50; monthly, about $114.83.
You can also start from a goal and work backward. Divide the goal by the weeks or paydays you have, then round up a few cents.
| Goal | Per week (52) | Per biweekly paycheck (26) | Per month (12) |
|---|---|---|---|
| $500 | $9.62 | $19.23 | $41.67 |
| $1,000 | $19.23 | $38.46 | $83.33 |
| $1,378 | $26.50 | $53 | $114.83 |
| $2,000 | $38.46 | $76.92 | $166.67 |
| $5,000 | $96.15 | $192.31 | $416.67 |
| $10,000 | $192.31 | $384.62 | $833.33 |
There are free per-paycheck charts in our bi-weekly savings challenges guide, and you can grab the bi-weekly savings challenge charts (PDF, 6 pages). No sign-up needed. Going bigger? The 10K savings challenge math breaks down every pay schedule.
Which Way Fits Your Budget?
Use your last two months of bank statements, not a guess. Look at how much was left the week before payday, then pick the version that fits that number.
Counting up or reverse fits if
- Your pay is about the same every week
- You like watching a chart fill in order
- You can start in the fall (count-up) or January (reverse)
- Your bills are covered with room left over
A flat or resized plan fits better if
- Your hours, tips or commission change a lot
- You are paid every two weeks and want one automatic transfer
- Week 52 at $52 already feels like a stretch
- You are saving for a dated goal like a trip or a holiday fund
Where to Keep the Money
A jar is fun for coins, but bills in a jar are easy to borrow from. Many people move the money to a separate savings account right after payday so it is out of sight. A savings account at a bank or credit union with deposit insurance is the usual choice for short-term money.
If you do keep cash, label an envelope with the goal and the date you want to reach it. Our envelope challenge guide shows how to run cash and a bank account side by side.
How to Stay on Track for 52 Weeks
Weekly 5-minute savings check-in
Missing a week is normal. The goal is the year total, not an unbroken streak. If a car repair or a sick kid eats a week, catch up over the next month instead of quitting.
Common Mistakes With the 52 Week Money Challenge
Starting in January without a plan for December. If you count up from New Year, set aside a little extra in summer so weeks 49 to 52 ($202 in total) are already covered.
Picking a step size that's too big. The $5 version sounds great until week 30 asks for $150. It's better to finish the half version than quit the double one.
Saving in the same account you spend from. The money tends to disappear. Even a separate free savings account at your own bank adds a little friction.
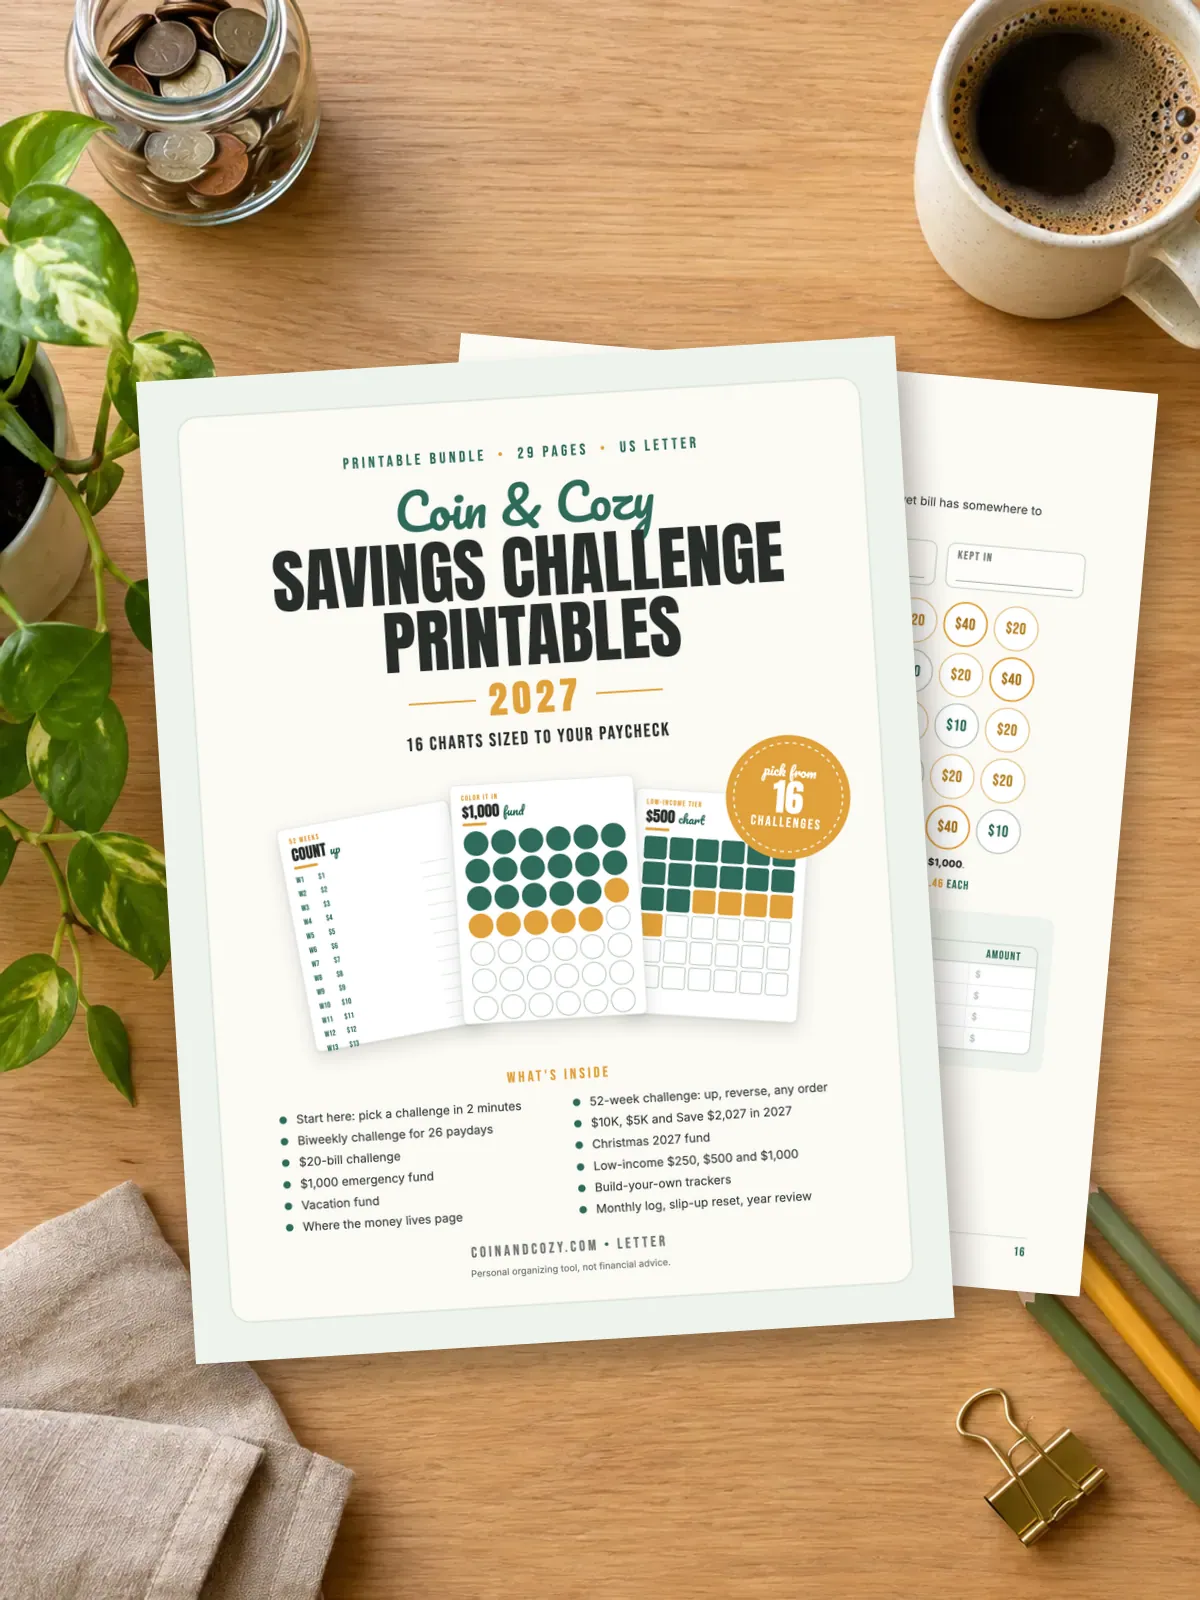
Want every version printed and ready? The savings challenge bundle includes the count-up, reverse and any-order charts, a per-paycheck chooser and smaller and bigger goal charts. If you want just the charts, our 52 week savings challenge printables page has free ones too.
Frequently asked questions
How much do you save in the 52 week savings challenge?
The classic version saves $1,378: $1 in week 1, $2 in week 2 and up to $52 in week 52. Half size totals $689 and double size totals $2,756.
What is the reverse 52 week savings challenge?
You start at $52 in week 1 and count down to $1 in week 52. It still totals $1,378, but the big weeks come first, so the end of the year is easy.
How do I do the 52 week savings challenge biweekly?
Save $53 every paycheck for 26 paychecks to reach $1,378. Or add two weeks together each payday, like $3 for weeks 1 and 2, then $7 for weeks 3 and 4.
Is there a 52 week savings challenge for low income?
Yes. Use smaller steps. The quarter version saves $0.25 to $13 a week for $344.50, and the half version saves $0.50 to $26 a week for $689.
When is the best time to start the 52 week savings challenge?
Any week works. If you count up, starting in the fall puts the biggest weeks in the next summer and fall instead of December.
Save it for later
Pin this to your Savings Challenges board so it's there when you need it.
Save to Pinterest